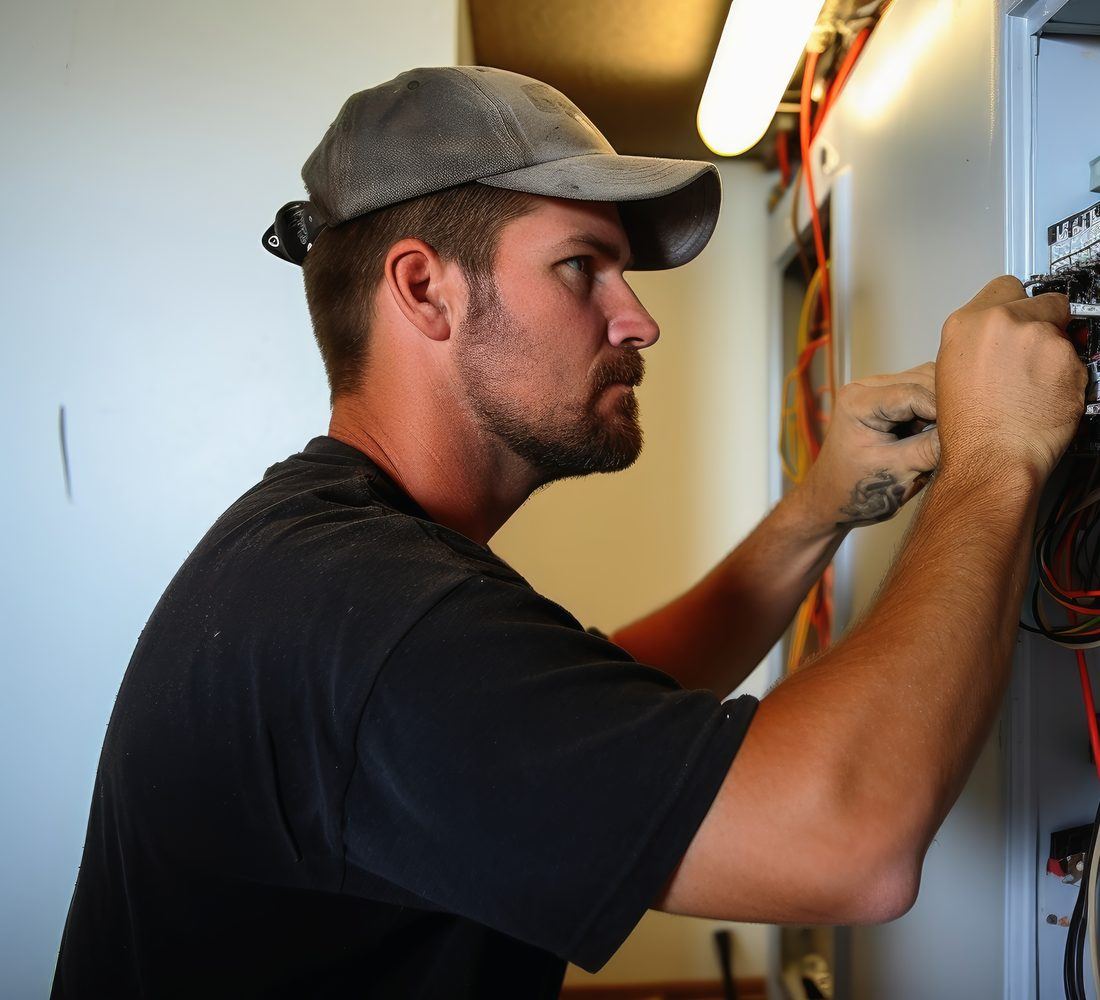
Electrician working inside an open wall on a residential service call

Work overtime
or shiftwork?

Blue-collar income is different.
Your lender should know the difference.

Overtime, prevailing wage, shift differentials, contract raises, occasional layoffs, hazard pay, etc. are part of life in the trades. We specialize in understanding that income and building a loan file that reflects the full picture for the underwriter.
Parents and two young children sitting on the front steps of their home

You may
need less
down than
you think

Low-down and zero-down
programs you may qualify for

Between FHA, VA, USDA and California down payment assistance, the twenty-percent rule you grew up hearing is often the wrong target. We'll lay out which programs you're eligible for, what each one costs over time, and which one leaves the most money in your pocket at closing.

A couple reviewing loan paperwork at a table with their loan officer

A lender
that keeps
your hours

Straight answers before
the gate opens

You shouldn't have to burn a personal day to talk to your loan officer. We take calls early, we take them after your shift, and you get our cell numbers instead of a queue. When something changes in your file, you hear it from us first — not from your agent three days later.

Loan programs

In a hurry to be pre-approved?

Skip the conversation and go straight to the full application. We'll build your pre-approval from it.

This is the complete loan application, submitted through Barrett Financial Group — the brokerage we operate under. It asks for your income, your employment history, your assets and the property you have in mind, so give yourself enough time to do it properly rather than starting it at a red light.

Have your pay information and an idea of your down payment on hand. If you're using overtime to qualify, your year-end pay stub is the document that does the most work. Once it's in, we aim to have your pre-approval back within one business day.

Not in a rush? Tell us about your situation first and we'll give you a straight answer before you fill anything in.

Straight talk

One hand resting on another as a loan document is signed

What pre-approval really means

A pre-qualification is an opinion. A pre-approval is a reviewed file. Here's the difference, why sellers care, and what to have ready before you ask for one.

A couple working through a household budget with a ledger and calculator

Down payment help in California

State and county assistance programs change often and run out of funding. A look at what's currently available, who's eligible, and how it stacks with an FHA loan.

Two people going through statements and a calculator at a kitchen counter

Rebuilding after a slow year

Layoffs, medical bills and a rough stretch on the credit report don't automatically disqualify you. What underwriters actually look at, and how long the clock runs.

Ready when you are

Start the form and we'll get you a real answer, not a sales pitch. It goes to a person, not a queue — and if you'd rather talk it through first, call (707) 977-0487.